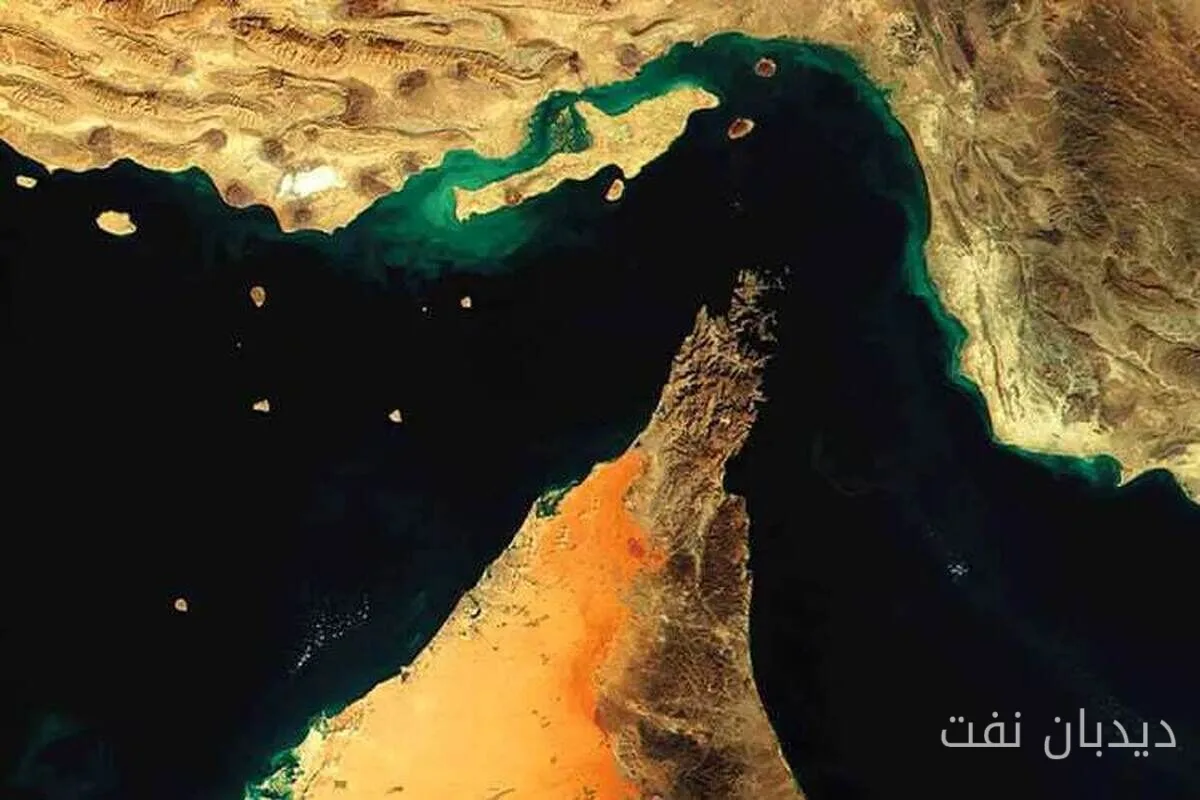
Tankers' earnings have reached their highest level, and reports indicate that global earnings for VLCCs (Very Large Crude Carriers) have averaged $600,000 per day. This increase in revenue is particularly observed due to the rise in transportation activities in the Strait of Hormuz and high oil demand in the global market.
Impact of Sanctions and Rising Costs
Over the past week, tanker earnings have grown by 3% to $66,421 per day for the ClarkSea index, reflecting an increase of nearly 50% compared to the end of August. This index is approximately three times its long-term average, and revenues in many key sectors remain at exceptional or strong levels.
Read more: 10% Increase in Oil Exports from Khark Terminal Amid Recent Conflict
Meanwhile, tanker revenues from the Strait of Hormuz have risen to between $800,000 and $1.5 million per day. Additionally, transportation costs have increased to about 15% of the value of each barrel of oil, compared to a historical norm of around 2%, indicating rising pressures on the oil market.
Demand Growth and Operational Challenges
MB Shipbrokers estimates the spot earnings for eco VLCCs at around $740,692 per day. Earnings for suezmax tankers have reached $334,811, and aframax tankers have reached $205,170. These conditions have arisen due to operational risks in the Middle East, reduced access to resources in the Atlantic, and longer voyages due to Asian refineries' need for oil from more distant sources.
Gas transportation revenues have also reached record levels, with VLGC (Very Large Gas Carrier) earnings currently on the rise. For example, VLGC earnings from Houston to Japan have reached about $189,700 per day, and earnings from the Persian Gulf to Japan have increased to over $219,000. These conditions have put additional pressure on the market due to a shortage of vessels and disruptions in energy flows.
In the car transportation sector, conditions have also approached record levels, contributing to the overall growth of the ClarkSea index. At the same time, dry trade has also made a significant contribution to this increase. Recent reports indicate that demand for loading capacity is increasing, while dry trade is expected to grow only 2.2% by 2026.
Finally, analysts predict that by 2026, due to delays and disruptions in supply chains, the market will remain under pressure and will not be able to fully resolve these issues before the peak of the Chinese New Year in January.
Read more: Iran Stands Firm on Its Position Regarding the Strait of Hormuz · Collection of Freight for Oil and Gas Shipments Suspended