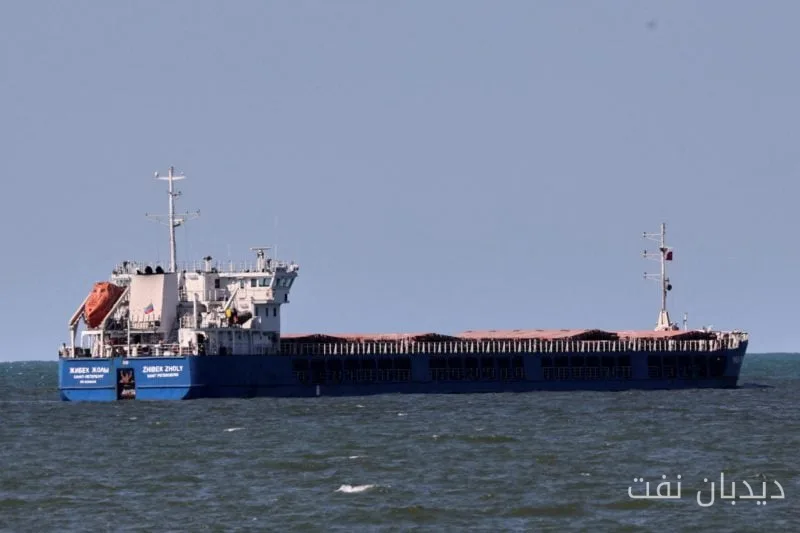
New analyses indicate that the container traffic crisis in Asia could seriously become a permanent problem, with expectations that this situation will continue until 2027. According to assessments by Sea-Intelligence, 8.5% of the global container fleet is currently affected by delays, equivalent to about 3 million TEU of capacity.
Challenges Arising from the Traffic Crisis
This Danish analyst has stated that history shows these disruptions will last for months rather than weeks. Based on the recovery rates observed after the pandemic and the initial Red Sea crisis, it is estimated that this crisis could last between seven to 10 months before returning to the low levels seen in June 2025. Accordingly, it is likely that the traffic crisis in Asia will only be partially resolved before the peak demand for freight prior to the Chinese New Year on February 6, 2027.
Read more: Energy Imbalance Management in Golestan with the Formulation of Seven Scenarios
Freight Rates in Asia
These bottlenecks have clearly manifested in freight prices within Asia. The Drewry intra-Asia freight index has reached its highest historical levels, and individual trades have also set new records. Recent assessments showed that freight rates from Shanghai to Laem Chabang have increased by 22%, reaching $1,609 for a 40-foot container, while freight rates from Shanghai to Jakarta have risen by 12%, reaching $2,300.
The recurrence of storms has contributed to this problem. Freightos analyses indicate that traffic from Far East origins has been severely pressured due to delays occurring at transit hubs, with brokers passing the pressure to other parts of the network as they navigate through heavily affected ports. Mid-September assessments warned that backlogs could continue well into October, following the Golden Week holidays.
Capacity Reduction and High Freight Rates
These disruptions are also evident in planned capacities. Sea-Intelligence estimates that Asia-North Europe freight capacity will reach about 1.5 million TEU over the Golden Week holidays, which is 27% higher than last year and 60% above pre-pandemic averages. These numbers are partly due to the bottlenecks created and not due to intentional capacity increases.
HSBC also predicts that this traffic will continue to impose effective capacity constraints through Golden Week, even as delays shift towards Southeast Asia and the Indian subcontinent. Meanwhile, Xeneta has reported Asia-U.S. rates near pandemic-era records. The company's senior analyst, Peter Sand, states that shippers entering 2027 tenders cannot ignore the ongoing disruptions as issues that will quickly disappear.
Charter Market Status
Charter markets tell a similar story. The BOXi Braemar index has reached its highest level in 52 weeks at 315.59, and brokers have described this situation as a "very tight supply situation," with virtually no post-Panamax or Panamax vessels available. Currently, massive orders are being hidden due to ships that are outside ports and waiting instead of carrying cargo.
Read more: 473 Billion Toman Loss to Industry from Energy Imbalance in 1404 · Canada's Oil Exports Shift Towards Asia: Trans Mountain Leading Changes